From Solidarity Savings to Real Impact: A Total Immersion Experience in Togo!

“I used to produce fewer than three bags of dried coffee. Now I produce more than ten.”

Every two years, SIDI invites its citizen shareholders and socially responsible savers to discover the real impact of their commitment during a one-of-a-kind trip. This year, about 20 participants will fly to Togo in early October to experience the reality on the ground firsthand.

On the agenda for this mission: in-depth discussions with our partners, as well as face-to-face meetings with their beneficiaries, who—thanks to their support—are able to develop their economic activities and earn a decent living.

Microfinance & Empowerment

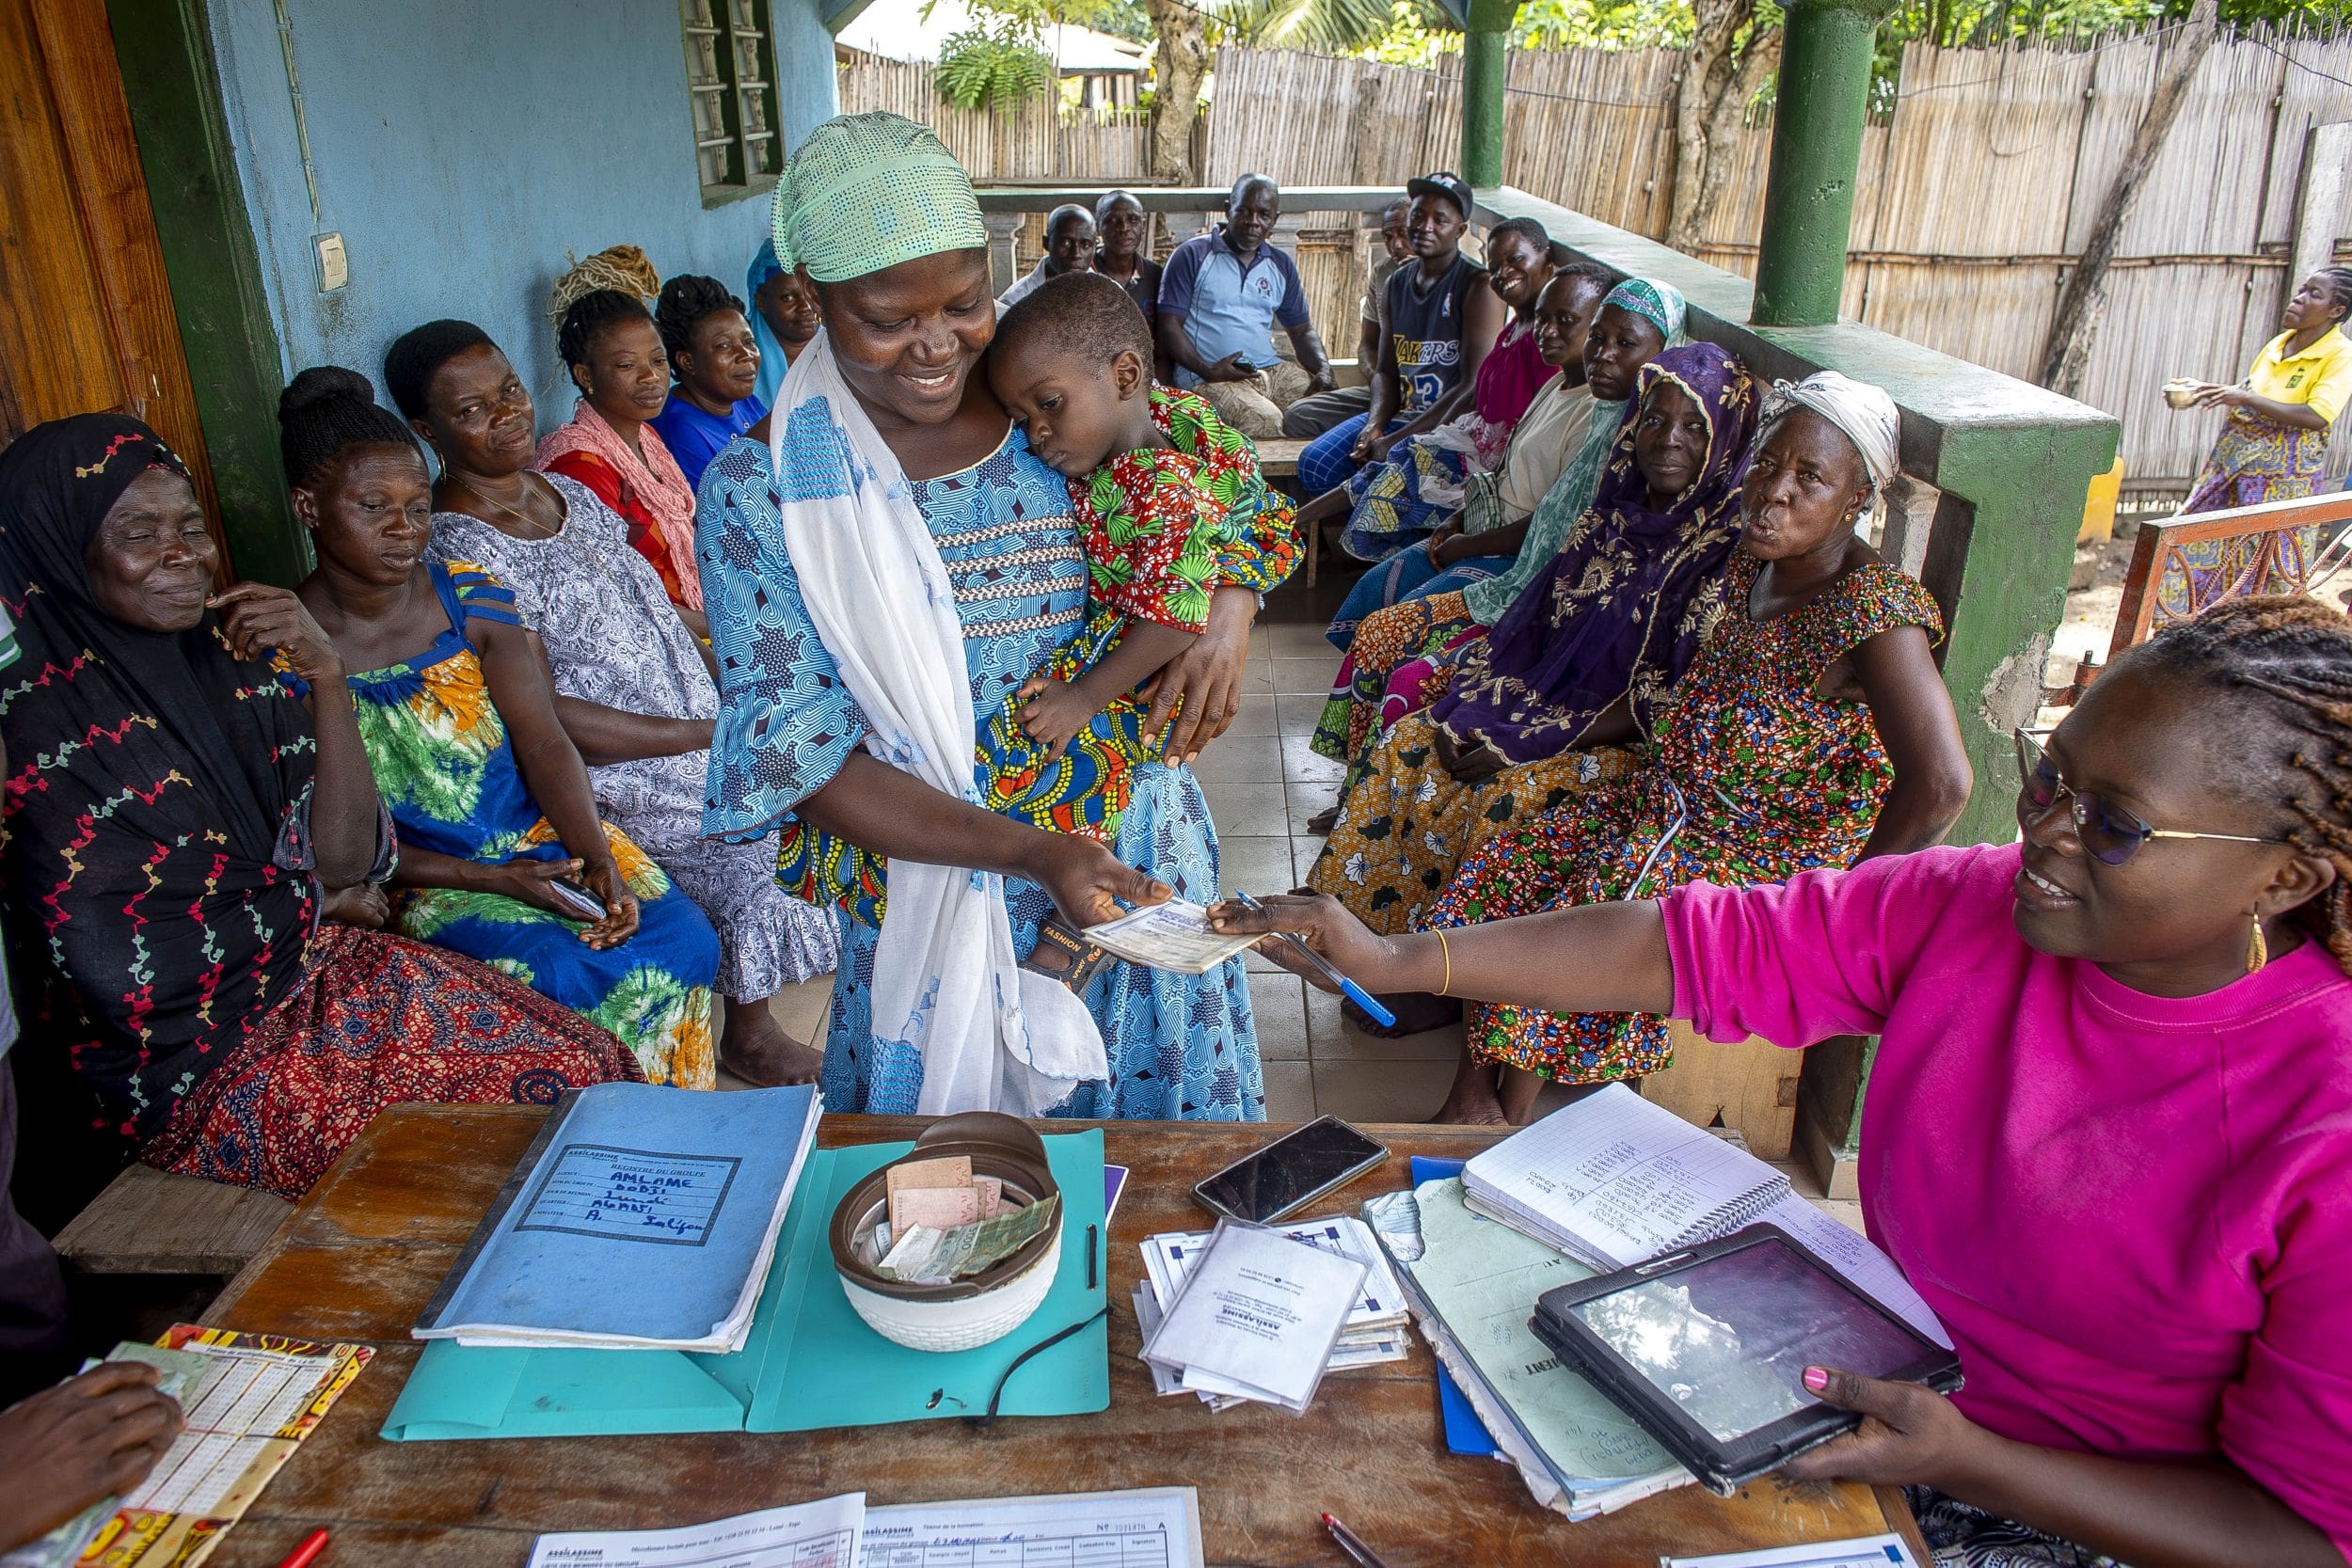
We learned about the work ofAssilassimé Solidarité in Lomé and Aného, which helps female microentrepreneurs living in extreme poverty grow their businesses. We also met with MECPIP (Mutual Savings and Credit Association for the Promotion of Private Initiative) and learned about its innovative community-based model, which relies on direct savings collection and tontines to support merchants and artisans. Meeting with Réseau MAIN, a pan-African network comprising 125 microfinance institutions. Its mission is to build the capacity of its members through exchange workshops and certificate programs.

Sustainable Agriculture & Fair Trade Supply Chains

We’ll meet with pineapple farmers, then head to Badou, a little further north, to meet farmers in the middle of the cacao harvest! There, we’ll meet the farming families who work with Gebana_Togo and Cocolomex, SIDI partners committed to fair and sustainable agricultural supply chains.

Finally, a meeting with partners from CCFD-Terre Solidaire in Lomé will provide a better understanding of their work focused on strengthening social dialogue in the country.

These on-the-ground encounters are a tangible reflection of the impact of solidarity-based savings. I can’t wait to share the stories from these encounters!

** Would you like to learn more about ways to support SIDI? Discover the benefits of our solidarity-based shareholding program. **

Uganda: Thirteen Years Later, SIDI Reinvests in Ugafode

“I used to produce fewer than three bags of dried coffee. Now I produce more than ten.”

This quote comes from a farmer supported by the Ugandan microfinance institution Ugafode. It perfectly sums up what goes on at the institution’s branches. Since 1994, Ugafode has chosen to establish a strong presence in rural agricultural areas, particularly in the western and southwestern parts of the country.

Thirteen years after we took a stake in the company, SIDI is increasing its stake alongside new international investors. A look back at a partnership that demonstrates just how much patience and close collaboration pay off.

Growth in Support of Our Social Mission

The recent figures speak for themselves: nearly 100,000 customers and 350 full-time employees; a loan portfolio that has doubled in three years to reach 30.8 million euros; and a very solid business model. But the company’s true success also lies in the high standards of its mission.

In an industry where the trend is toward urban concentration, Ugafode has taken the opposite approach: 60% of its clients live in rural areas. More than half of its loans (51%) finance agriculture. By supporting this rural momentum, Ugafode enables thousands of small-scale farmers and rural microentrepreneurs to generate value in their communities, thereby contributing to a transition toward a more equitable economic model.

Tangible results: 86% of clients see their incomes increase[1]. In addition, 27% of them report a marked improvement in their quality of life, and 15% report greater resilience in the face of economic shocks. And business is growing enough to create jobs: the average number of employees per client has risen from 2.2 to 4. Ugafode doesn’t just provide financing to individuals—it helps shape the local economy.

[1] Ugafode participated in the 60 Decibels Microfinance Index in 2023, a leading organization in measuring customer perception in the microfinance sector. This data is derived from that index.

Inclusion that leaves no one behind

What sets Ugafode apart is its ability to serve some of the most vulnerable populations.

  • Refugees: The organization is a pioneer in this field, with two of its offices located directly in the camps, helping to restore financial independence to populations facing extreme hardship.
  • Women: The loan program specifically designed for them has been a great success and now accounts for nearly 30% of the portfolio.

This social commitment is at the heart of Ugafode’s business model. And it is precisely this alignment with SIDI’s values that has motivated our decision to stand by Ugafode for the past thirteen years and to reinvest in the company this year.

SIDI: A Long-Term Commitment

The road hasn’t always been easy. Health crises, agricultural epidemics, operational challenges: Ugafode has weathered some turbulent times. It is in moments like these that a shareholder’s commitment is truly tested. Where others might have sought a quick way out, SIDI chose loyalty.

We have stayed the course, convinced by the quality of the management team and the soundness of the model promoted by Ugafode. This consistency sent a strong signal. It reassured the market and opened the door to leading institutional investors, such as the Norwegian sovereign wealth fund through Abler Nordic, which is now taking a stake in the company. Our long-standing presence has served as a mark of trust and validated Ugafode’s strength in the eyes of international impact finance stakeholders.

SIDI’s Support: A Catalyst for Transformation

In keeping with its business model, SIDI is providing Ugafode with long-term support by combining equity investment, financing—notably through the FEFISOL fund—and the provision of consultants to assist with the institution’s governance and transformation.

This long-term commitment proved particularly crucial during the difficult periods the MFI faced. In 2014, SIDI appointed a volunteer consultant, Michel Dubois, to represent it on Ugafode’s board of directors. A former finance professional, he supported the institution during the management crisis it faced in the late 2010s, marked in particular by the departure of the director at the time. Deeply involved in governance, Michel Dubois helped strengthen governance practices, secure the portfolio, and put a new management team in place.

Since 2019, Richard Emuye, a Ugandan consultant and digital transformation expert, has represented SIDI on the Board of Directors. As the institution faced major challenges related to cybersecurity, system modernization, and digital fraud prevention, he chaired the Innovation and Digital Transformation Committee. His expertise has notably contributed to strengthening the security architecture and accelerating the institution’s digital transformation. The results speak for themselves: Ugafode is the only regulated institution in Uganda to have experienced no cybersecurity incidents since 2021.

These efforts have enabled the institution to achieve several key milestones: stabilizing its banking system, digitizing informal savings groups in underserved rural areas, rolling out a mobile banking service—now actively used by 90 percent of registered users—and implementing online tuition payments.

Ugafode’s experience thus provides a concrete example of what SIDI’s support brings to the table: in times of crisis as well as during periods of transformation, its administrators—whether volunteers or local representatives—devote their expertise and time to strengthening and developing its partners. “There is no doubt that Ugafode is now a strong and resilient institution,” says Richard Emuye. SIDI’s long-term commitment has contributed to this resilience.

On to the next section

Today, Ugafode is gaining traction. The ongoing capital increase is not intended to change the company’s strategy, but rather to build on its existing success: deepening its rural presence, expanding its impact on women and refugees, and continuing to drive digital innovation.

For SIDI, this increased involvement is the logical next step based on a firm belief: when solidarity-based investment is patient and combined with on-the-ground expertise, it helps build local institutions capable of bringing about lasting change in people’s lives. Ugafode is a perfect example of this.

** Would you like to learn more about ways to support SIDI? Discover the benefits of our solidarity-based shareholding program. **

Field Report: In Burkina Faso, SIDI is active in areas where few investors venture

Mission Burkina Faso - Jacques Afetor

Every quarter, SIDI publishes an article highlighting a field mission carried out by one of its partnership officers. Today, SIDI shares the account of Jacques Afetor, SIDI’s West Africa partnership officer since 2023, based in Lomé, Togo. These field visits are key opportunities to gain an insight into local realities, assess the challenges faced by stakeholders, and discuss future prospects. They also provide an opportunity to share our partners’ achievements more widely.

I am fortunate to be very familiar with the microfinance sector in West Africa, since before joining SIDI, I worked for more than ten years at Assilassimé, a social microfinance institution that partners with SIDI. Being in the role of a funder adds a new dimension, offering the opportunity to support not only the growth of our partner microfinance institutions but also that of agricultural entities involved in various value chains across the subregion.

Given the security situation and the information provided by the Ministry of Foreign Affairs, which advises against all travel, my departure for a mission to Burkina Faso remained quite uncertain.

However, discussions with my contacts on the ground provided a more accurate picture of the actual situation in the country, which made it easier to plan the mission and take appropriate measures to mitigate risks.

Burkina Faso: The Land of Honest Men Faces Several Challenges

Before I tell you about the visits we made to our partners, I think it’s important to provide some background on the situation in Burkina Faso. The country has faced a particularly tense security and political climate in recent years. Although an improvement was observed in 2025 in the capital and the southwestern part of the country, the situation remains very fragile.

In 2023, more than 40% of the population lives below the poverty line, according to the World Bank. Burkina Faso ranks 186th out of 193 countries on the United Nations Development Program’s Human Development Index (HDI). Investors remain few in number and out of reach for most microfinance institutions, such as the country’s small agricultural cooperatives.

More than two million people are either internally displaced or have sought refuge abroad, representing over 10 per cent of the population. Despite this situation, SIDI remains committed to its mission of supporting the development of income-generating activities for those who need them most.

Getting to know ACEP: the Credit Agency for Private Enterprise in Burkina Faso

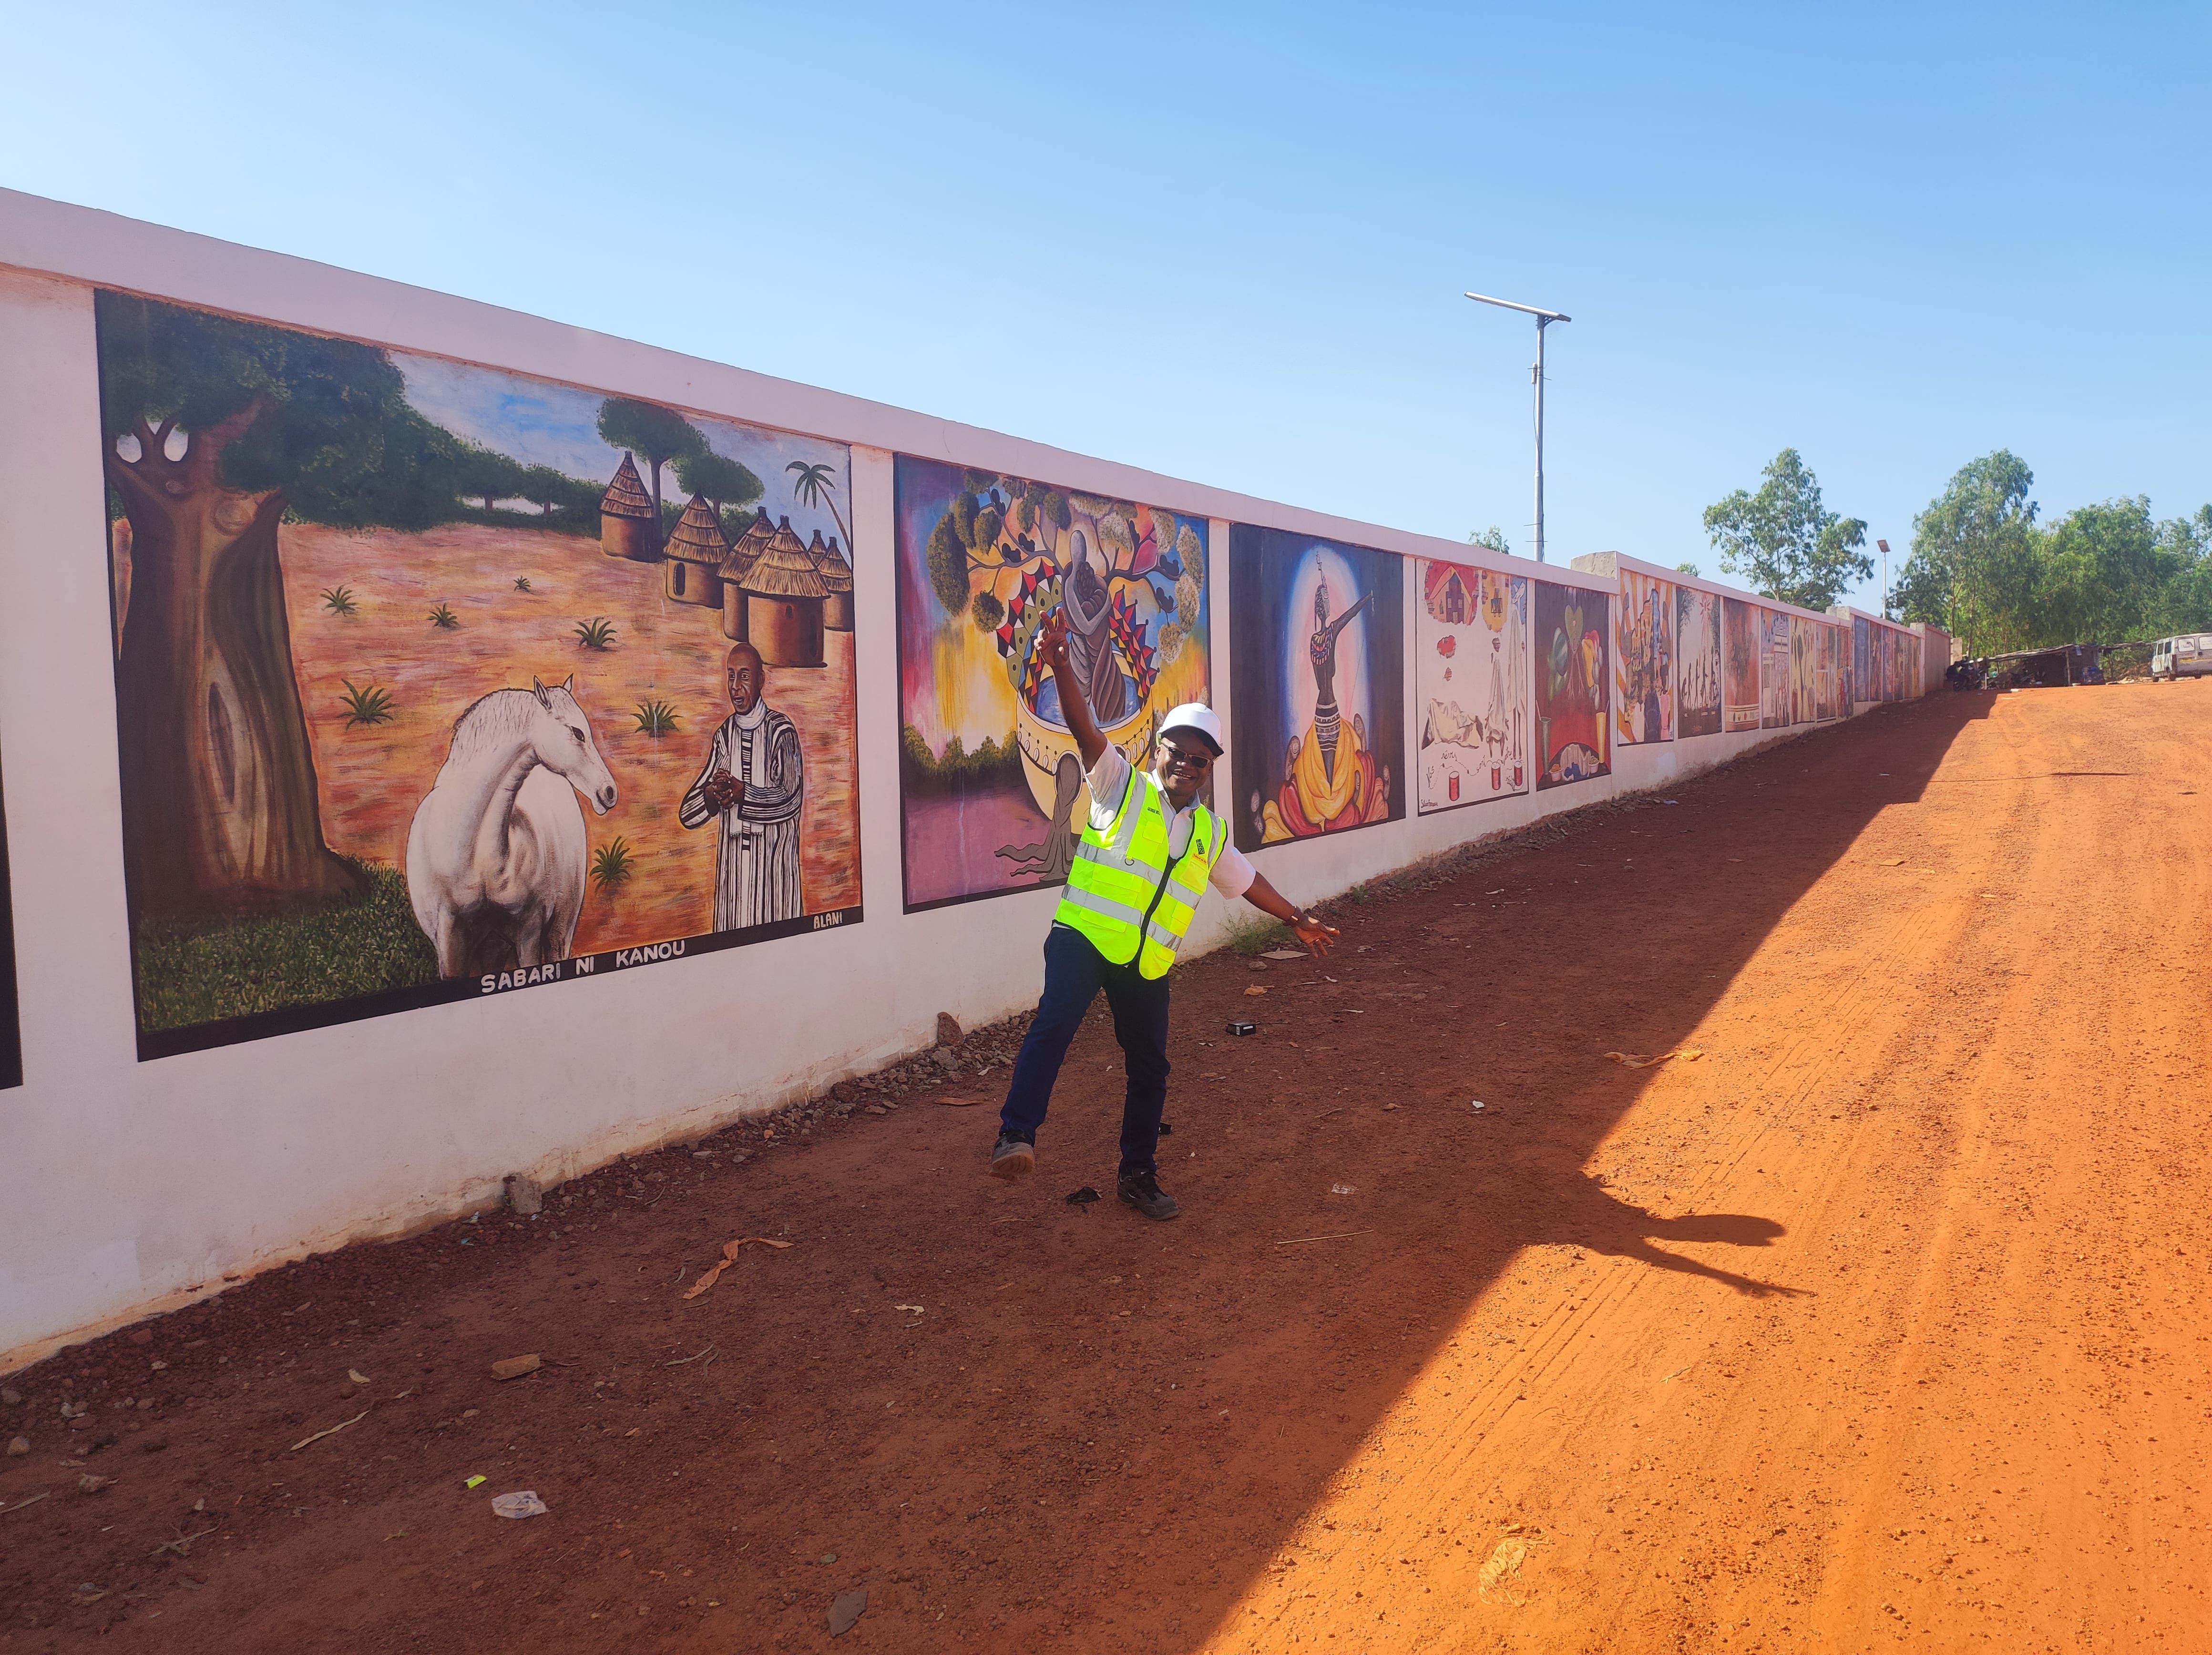
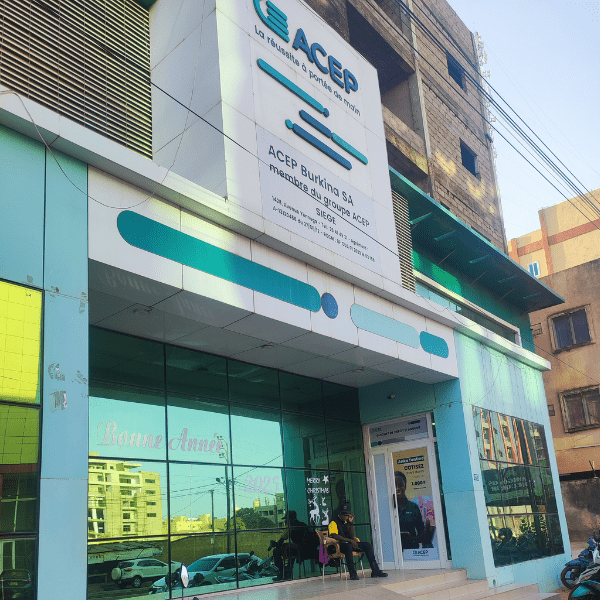
I began my series of visits with ACEP Burkina, whose head office is in Ouagadougou, and two of its 14 branches based in Bobo Dioulasso, in the west of the country. The institution’s core business is providing finance to micro and small enterprises, which are generally overlooked by banks.

ACEP Burkina Faso has been a partner of SIDI since 2021. SIDI also acquired a stake in ACEP in 2022, confirming its commitment to strengthening this partnership and providing the best possible support for the microfinance institution’s strategic decisions.

ACEP-BF (3)
ACEP-BF (9)
ACEP Burkina Faso 2025

ACEP is facing cash flow difficulties due to the scarcity of foreign investment in Burkina Faso, which has led to a slowdown in the development of its activities in 2025 compared with initial forecasts.

Lors de ma visite, j’ai néanmoins été impressionné par la résilience de notre partenaire qui a su développer de nouveaux produits financiers adaptés aux clients individuels et ainsi diversifier ses sources de revenus. En guise d’exemple, ACEP propose des solutions de crédit via le mobile ne nécessitant pas de garantie. Elle met aussi à disposition des automates de dépôt d’argent pour faciliter l’épargne à ses clients et a lancé le déploiement de son nouveau produit d’épargne tontine qui consiste à faire la collecte de la petite épargne régulière auprès de ses clients. Le leadership de l’équipe dirigeante, ainsi que la détermination et l’engagement du personnel, permettent à ACEP de conserver un ancrage solide dans le secteur de la microfinance au Burkina Faso, malgré un environnement particulièrement contraignant. Cette résilience motive en partie la SIDI à poursuivre son accompagnement via son fonds FEFISOL.

ACEP’s Environmental and Social Performance Management

Since my last visit less than two years ago, ACEP has strengthened its commitment to managing its social and environmental performance by appointing a dedicated officer to oversee these issues. It has also carried out an impact assessment in collaboration with the consultancy firm 60 decibels, which has enabled it to evaluate the effects of its financial services on its clients.

As such, 41 per cent of them say that their standard of living has improved thanks to the growth of their businesses, which has had a positive impact on their households, and 73 per cent of customers have taken out a loan for the first time.

I see this as a positive sign: these results confirm that ACEP’s strategy is aligned with SIDI’s mission, which prioritises communities excluded from conventional economic and financial systems, particularly rural communities, women and young people.

Furthermore, ACEP also does outstanding work in providing finance to stakeholders in local agricultural value chains, particularly SMEs operating in various sectors such as rice, cotton, cashew nuts, fruit and vegetables. By providing finance to these SMEs, ACEP indirectly reaches thousands of small-scale producers who help to strengthen food security for local communities.

Second stop on the tour of Gebana Faso: a 100% organic agricultural revolution supporting local communities

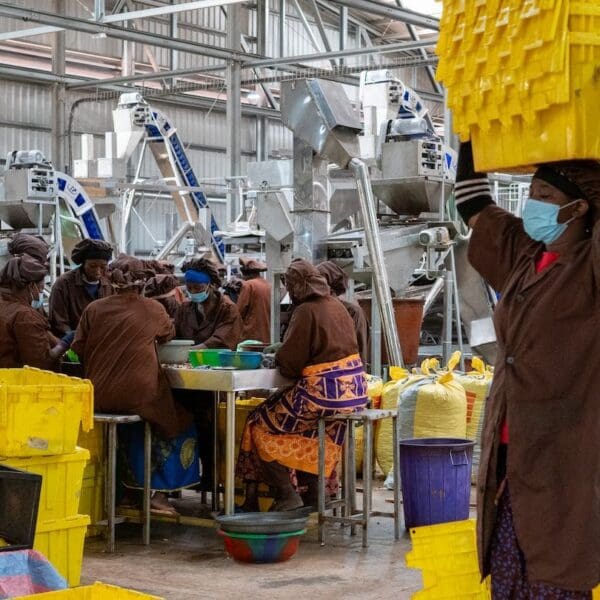
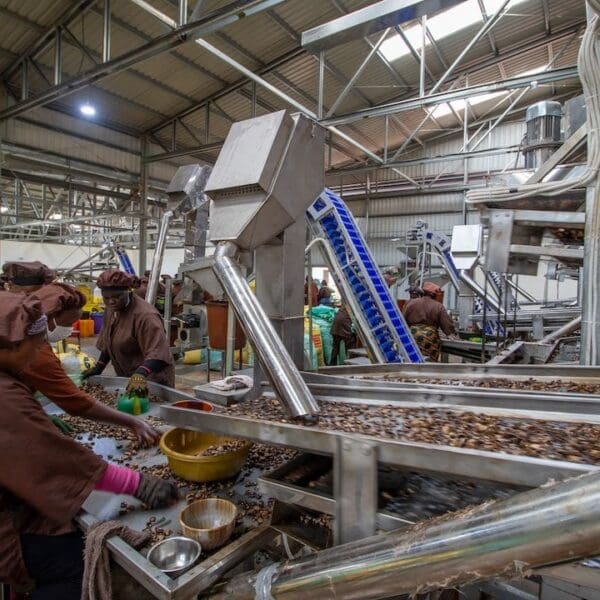
I had the opportunity to meet with the team at Gebana Faso, a company that specializes in processing cashews and dried mangoes. Gebana Faso has been a partner of SIDI since 2019. Our two organizations share strong values in support of environmentally friendly family farming that can strengthen the local economy by creating sustainable jobs in these regions.

Today, 100 per cent of production is certified organic. Gebana Faso sources its produce from several regions across the country, mainly from more than 5,000 family farmers organised into producer cooperatives.

The ‘Belle Usine’: the realisation of a major project

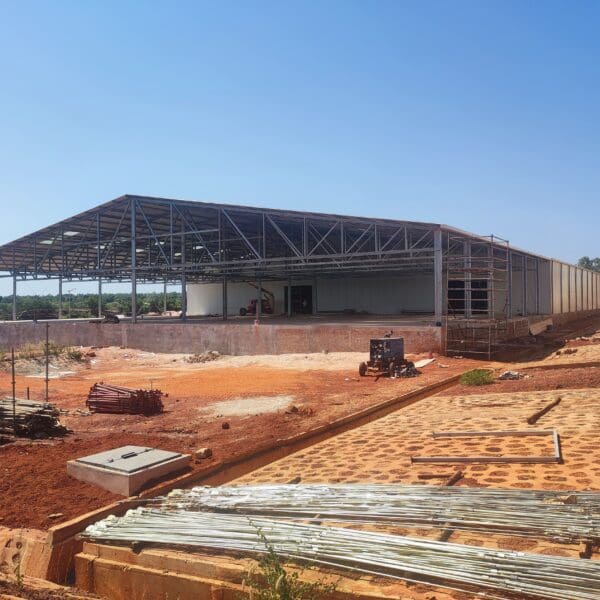
The construction of the Belle Usine, as I like to call it, was completed in early 2026 and I was lucky enough to be able to visit it: it will enable us to increase production capacity, boost the volume of produce processed (from 1,500 tonnes of raw nuts processed in the old factory to a capacity of 7,000 tonnes in the new one), create over 100 additional local jobs, whilst increasing the number of smallholder partner producers by more than 20 per cent. As for mango drying, there are 60 processors employing over 4,000 people. In 2026, this new factory will take on part of this activity, which is usually outsourced. In total, Gebana Faso’s operations generate income for over 1,000 households.

Usine Gebana Faso 2026 ©Gebana
Usine Gebana Faso 2026 - 1
La Belle Usine Gebana Faso 2025

A fairer economic model for local producers and employees

Gebana Faso has successfully developed supply chains in which local producers play a key role. For example, they benefit from a number of financial incentives: a bonus of €15 per tonne sold, an impact bonus of €75, and a selling price to Gebana Faso that is 10 per cent higher than average market prices.

Gebana Faso’s employees enjoy social benefits and paid leave, and travel to the production site every day on special shuttle buses chartered from the town of Bobo Dioulasso, which is about twenty kilometres away.

Reducing the environmental and climate impact

  • With its new factory, Gebana Faso will now be able to recycle all of its production waste (raw cashew nut shells and mango skins), which will be used to roast the nuts. This practice helps to significantly reduce air pollution, in particular by limiting CO₂ emissions.
  • At the same time, Gebana Faso is setting up ‘field schools’ to train farmers in agroforestry practices – a method of farming that provides better soil protection and reduces the carbon footprint.
  • A project to set up a composting centre for mango peelings is also currently being developed, with tests already yielding positive results.
  • Training courses in agroecology are provided for farmers to offer them technical and operational support

Through its activities, Gebana Faso demonstrates that it is possible to develop an agricultural sector that is ambitious in economic, social and environmental terms, despite a challenging context.

Following this field visit and the various analyses carried out, it was decided to grant new loans totalling 1 million euros through the FEFISOL II fund to Gebana Faso and ACEP, making SIDI the sole foreign investor to commit to supporting them.

This is a mark of trust that is deeply rooted in SIDI’s DNA: to provide support by demonstrating flexibility, boldness and innovation, in order to stand by our partners despite the risks and the fragile circumstances in which they operate.

I have real hope for Burkina Faso and its people because there is a palpable sense of dynamism. When you meet people there, you really get a sense of the strong determination that exists to bring about change, to create value and to improve people’s living conditions.

Palestine: the challenge of supporting economic activities in wartime

SIDI has been supporting partners in the Israeli-occupied Palestinian territories since 1988! But SIDI quickly realized that any investment in Palestinian micro-businesses - extremely risky in the absence of a just peace in the region - would only be viable if a guarantee mechanism was put in place to secure these loans and cover the microfinance institutions against losses linked to the occupation.

Understanding the financial tools deployed by SIDI

SIDI has several financing tools at its disposal to support the activities of its partners. For SIDI, “equity investments” consist in acquiring a stake in the capital of partner companies, in order to strengthen their equity capital and support them in their long-term development.

Loans” enable our partners, in particular producer organizations, to pre-finance their members’ harvests.

So what is Daman? Through this article, we wish to highlight this Palestinian guarantee fund, an unusual and innovative means of financial resistance, which, on its own scale, attempts to support the most vulnerable civilian populations.

A little history…

It took almost 10 years to create Daman in 2015, a Palestinian company whose shareholders were initially SIDI, ACAD Finance and ASALA (the latter two being SIDI’s partner Palestinian microfinance institutions). In 2019, the Daman guarantee fund is being replenished thanks to initial co-financing from the Luxembourg government and the NGO CPJPO[1], enabling it to scale up.

One of the main strengths of the Daman guarantee fund is that it has identified “political” risk, i.e. the deleterious effects of the violent occupation of Palestine by the Israeli army, as the main risk to be covered for Palestinian micro-enterprises.

Of course, the initiators of Daman, both at SIDI and ACAD Finance, never imagined that after the bloody and murderous Hamas attack in 2023[2], the terror imposed by Israel, which amounts to war crimes, crimes against humanity and even genocidal risk, would “wipe out” part of the population[3] and the entire infrastructure[4] of the Gaza Strip.

The guarantee fund patiently built up thanks to subsidies from Luxembourg has proved insufficient to meet needs in Gaza, but also in the West Bank, where joint pressure from settlers, the police and the army is leading to violent events and the physical isolation of Palestinian communities and towns. This is a challenge for Daman and especially for its future financing, but it does not prevent it from operating and “doing its bit” in a sometimes dramatic context.

[1] Committee for a Just Peace in the Middle East – https://paixjuste.lu/

[2] Over 1,200 dead, mostly Israeli civilians

[3] 72,000 dead and 180,000 wounded, mostly women and children

[4] 92% of buildings destroyed

How does the Daman guarantee fund work?

Each year, depending on the amounts available, Daman allocates a sum to each of the three Palestinian microfinance institutions: ACAD, ASALA and REEF. These three microfinance institutions inform Daman of the outstanding loans which will benefit from this coverage and which meet the repayment criteria. No money is transferred. This is the maximum global sum that the microfinance institution can claim from the guarantee fund, if it ever demonstrates that its client has been unable to pay its loan because of the Israeli occupation.

Conditions for repayment and cancellation of Daman guarantee fund debts

The Daman guarantee fund doesn’t repay just anything and everything. Insured” loans must be under US$10,000, for a maximum of 48 months, for income-generating activities. Consumer loans are excluded. Daman reimburses only the principal, i.e. unpaid interest is assumed by the microfinance institution. If the customer has been in default for more than a year, then the microfinance institution can turn to the Daman guarantee fund to request repayment. And if the customer was already in default (late payments) before the “accident of life” linked to the military occupation, the loan is not eligible for repayment.

For their part, microfinance institutions contribute 1.5% of the guaranteed portfolio to Daman’s costs.

In the field, concrete examples to illustrate the situation

Mohamed H applied for a loan of US$4,000 for his cage-making workshop, which enables him to raise poultry. During the attack on the Tulkarem refugee camp in early 2025, Israeli bulldozers razed his workshop to the ground. Mohamed H lost everything.

There’s also the story of Assel A, who had taken out a loan to invest in her market gardening activities by installing a greenhouse. The village where she lives was “closed” by settlers for a few days. She was unable to access it and irrigate the fields. The entire harvest was lost, and the tarpaulins were lacerated by the settlers.

These two customers are unable to pay their loans, and provide a concrete illustration of the colossal difficulties encountered by Palestinians in maintaining an income-generating activity in the context of war.

The microfinance institution that granted the loan can then submit a claim for reimbursement to the Daman guarantee fund by preparing a file. If the claim is admissible, Daman appoints an “expert” to verify the veracity of the facts. If the report is favorable, Daman can then disburse the funds to the microfinance institution and cancel the customer’s debt. Around 85% of applications submitted by microfinance institutions to the Daman guarantee fund are accepted.

This makes it easier for Palestinian microfinance institutions to rely on this mechanism, which covers part of the financial risks incurred. By reassuring Palestinian microfinance institutions, it is ultimately vulnerable populations who benefit more easily from loans to invest in income-generating activities, despite the war.

In 2024 (annus horribilis given the total losses recorded in Gaza), Daman was able to compensate $332,623 from 386 customers of the three microfinance institutions[1]. To conclude, let’s give the floor to the evaluator commissioned by :

The evaluation of the project shows that, despite all the constraints linked to the context, Daman remained operational and played a stabilizing role by enabling MFIs to benefit from its risk coverage. This enabled them to lend to very vulnerable customers, which would probably not have been possible without Daman.[2].

The big challenge remains: how can Daman be sustainably capitalized to meet the very specific needs of a zone of war and occupation such as Palestine? This is what Daman and its shareholders need to do!

[1] US$634,000 since the start of the Daman operation

[2] Project evaluation of Daman for SME’s by MFR


Kitagata: a Ugandan cooperative promoting resilient agriculture

Who’s Kitagata ?

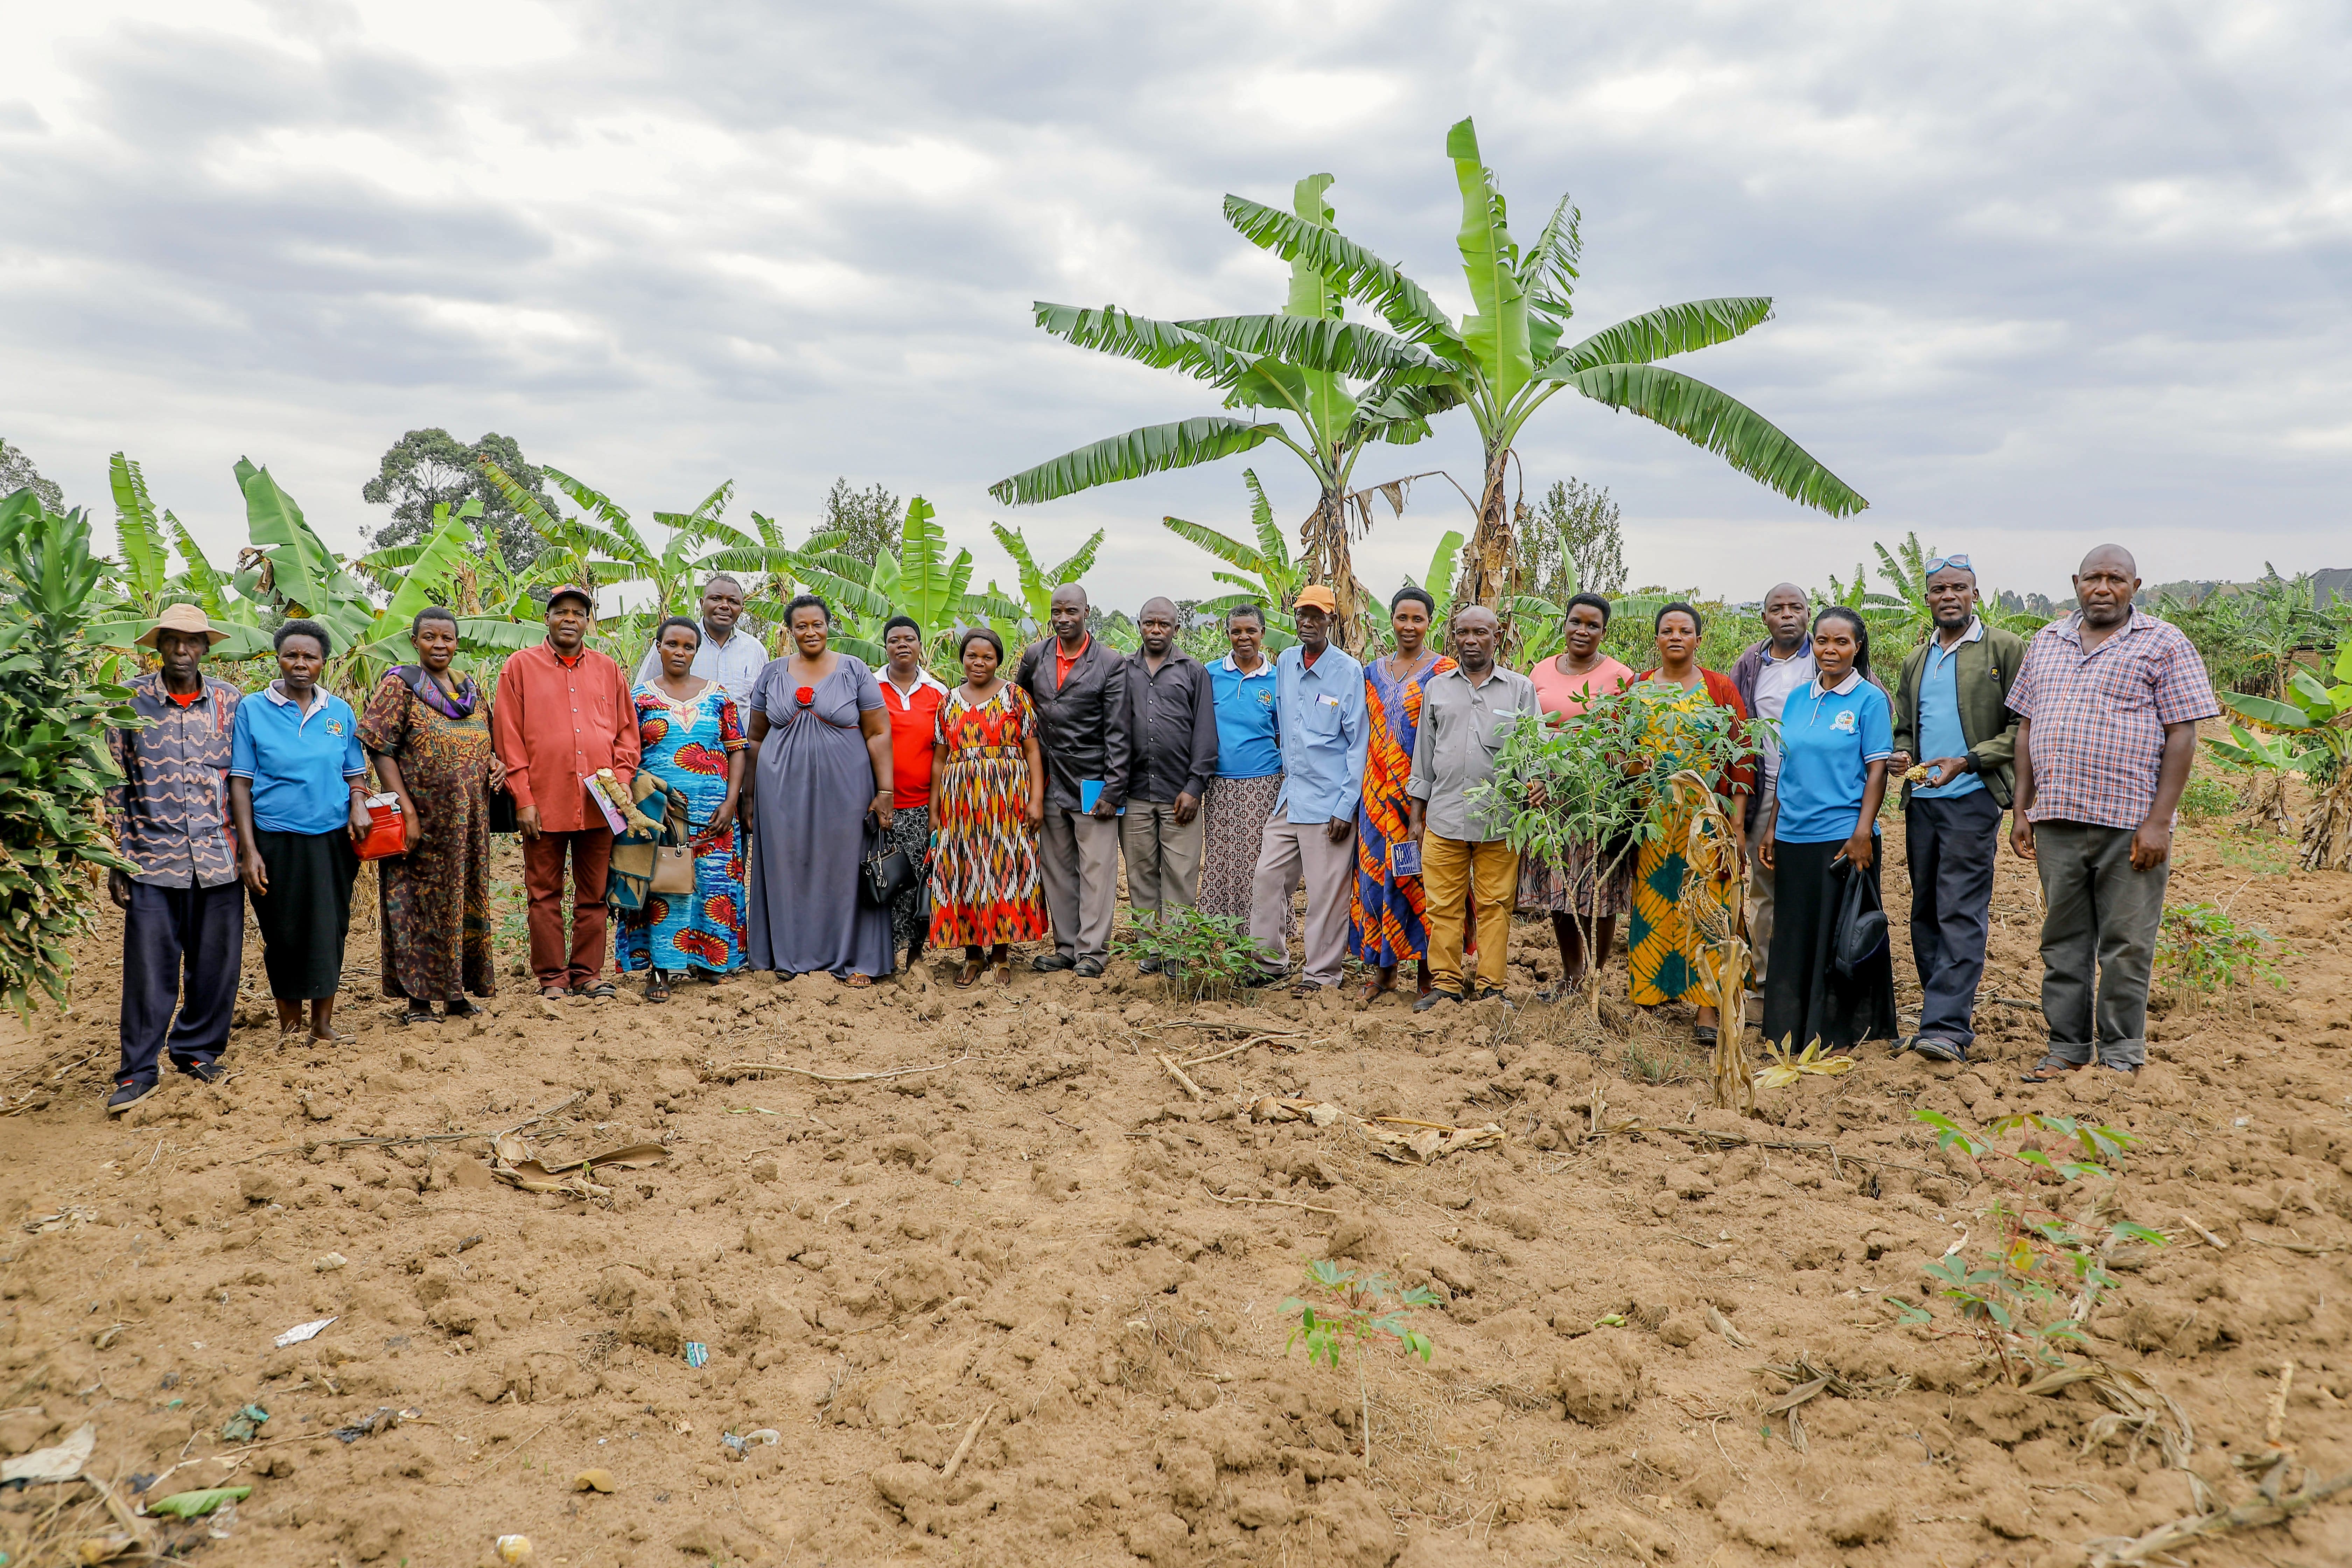
In southwestern Uganda, the Kitagata Mixed Farmers cooperative plays a key role in improving food security and incomes for smallholder farmers. Created in 2013 on the initiative of the farmers themselves, it meets a fundamental need: to have a common space to share the challenges encountered in the field, build collective solutions, and have greater influence with local economic actors. SIDI supports this partner through its locally based branch in Kampala, Soluti. Kitagata mainly sells millet and beans to Ugandans.

A diversified offering for members

Initially active in the Sheema district, Kitagata has gradually expanded into the neighboring districts of Bushenyi, Mitoma and Rubirizi, with a simple rationale: to pool efforts, increase production volumes collected, and better defend the interests of its members. Its vision is clear: to promote local food production and fight hunger, in a context increasingly constrained by climate change.

In addition to market access, the cooperative has developed a diversified range of services to best meet the needs of its members: literacy sessions, training in financial management, and assistance in structuring small village savings groups and
credit. In 2024, Kitagata also began granting cash advances to producers, enabling them to meet the needs of the agricultural season.

Kitagata is strongly committed to promoting gender equality. Women account for 66% of the cooperative’s beneficiaries, and specific programs are set up to meet their needs as effectively as possible: this is particularly true of certain groups of widows, who are a very vulnerable group in Uganda, and to whom the cooperative provides additional services.

Facing up to climate challenges

In recent years, the farmers supported by Kitagata have been particularly hard hit by the vagaries of climate change: unpredictable seasons, droughts and declining soil fertility. These shocks severely affect the production of food crops such as millet, maize and beans. Faced with this reality, the cooperative has chosen to become actively involved in promoting more sustainable agricultural practices, adapted to local conditions.

Thanks to the presence of two agronomic technicians on its team, Kitagata raises awareness of environmental issues and supports its members in implementing agroecological techniques: crop rotation,
interculture, use of organic manure, mulching, responsible management of wetlands, rainwater harvesting and storage. This support is provided either on an individual basis, to meet the specific needs of producers, or collectively, in areas specifically dedicated to training, known as “demo gardens”.

A structuring project with SIDI

In 2024, SIDI supported the cooperative in strengthening its social and environmental commitment thanks to a structuring program funded by SSNUP, designed around several complementary components:

– Economic and social: to diversify producers’ income and strengthen their resilience in the face of climate change, the cooperative has set up training in cassava cultivation, an emerging sector with high potential and adapted to local climatic conditions.

– Gender component: training for trainers in the GALS (Gender Action Learning System) participatory methodology was organized. This community-based approach aims to empower women and men, and combat gender inequalities in households as well as within organizations.

– Environmental aspect: the cooperative has launched an agroecology training program, specifically applied to cassava cultivation, for its small-scale producers.

Some key figures about Kitagata

Key Figures Kitagata - 582 producer members
Key figures Kitagata Uganda- women
Key figure Kitagata Uganda - revenue 2024
Key figures Kitagata Uganda - local sales on the market
Key figures Kitagata Uganda - financial training 2025
Key figures Kitagata Uganda - gender training for staff and board members
Key figures Kitagata Uganda - 329 trained agroecology cassava cultivation
Key figures Kitagata Uganda - gardens installed

In Kenya, our partner Yehu Impact Limited receives an award from the international agency MicroFinanza Rating

In Kenya, Yehu Impact Limited, a partner of Soluti, SIDI's subsidiary for East Africa, recently obtained certification for its commitment to protecting vulnerable clients.

What role do international rating agencies play?

Since the late 2000s, rating agencies have developed along the lines of their conventional financial counterparts, to ensure that microfinance institutions follow sound management practices. Indeed, against a backdrop of massive demand for financial services from small-scale entrepreneurs in the informal sector, some players may have seen this as a huge market with more potential for profit than impact… as evidenced by the recurrent scandals in certain countries that have been reported in the media.

These agencies, including MicroFinanza Rating, a pioneering leader based in Milan, play an important role in this respect, since they analyze in detail the data and practices of microfinance institutions, leading to an independent rating. More importantly, they help to spread best practice in the sector, leading to the development of internationally recognized standards. These standards are then set by the Social Performance Task Force, an NGO that brings together all the players involved.

Customer protection: what exactly are we talking about?

One of the major challenges of these best practices is to protect customers. Vulnerable populations, often poorly educated in financial matters, can easily fall into spirals of over-indebtedness, or even be the target of fraud. These standards will therefore ensure that the microfinance institution takes every measure in its power to prevent a beneficiary from becoming over-indebted.

Similarly, microfinance institutions must ensure that customers can fully understand the conditions of the loans (rates and various fees, procedures in the event of arrears, etc.) they are about to take out. For example, microfinance institutions offer contracts in local languages, with explanations given orally and not just in writing. This set of best practices has been brought together in a recognized standard known as the “Client Protection Pathway”.Client Protection Pathway“.

In Kenya, Yehu Microfinance rewarded for its efforts to help the most marginalized populations

Kenya is East Africa’s leading economy. It is a leader in technological innovation to enable financial inclusion of marginalized populations, with the invention of “Mobile Banking”, i.e. the possibility of paying or saving with a simple cell phone, long before the arrival of smartphones. Microfinance has also been developing very dynamically for over 20 years, but without any real regulatory framework.

By obtaining the silver level of ” Client Protection Certification “, Yehu Impact Limited demonstrates that it has met and exceeded a set of rigorous criteria on the quality and ethics of its practices to protect its clients. This recognition reinforces Yehu Impact Limited’s credibility in terms of social impact: the money invested serves the development and autonomy of vulnerable communities, and their economic integration.

Who is Yehu Microfinance?

Yehu Impact Limited is a microfinance institution founded in Kenya in 1998 by Choice Humanitarian, an international NGO. It began its activities by organizing women’s groups and facilitating their access to savings. Today, Yehu Impact Limited reaches over 70,000 beneficiaries, mainly rural women, with the aim of empowering their communities through affordable, sustainable and socially responsible microcredit.

Yehu Impact Limited provides financial education to the most vulnerable populations through a series of training courses on financial management. In this way, the microfinance institution supports the creation of income-generating activities in agriculture, green energies, micro-insurance and other areas.

SIDI is particularly proud of the Yehu Impact Limited teams’ commitment to inclusive finance. This client protection certification is part of the recognition of this microfinance institution’s efforts to empower the most marginalized communities in rural Kenya.

Back from mission: in Ivory Coast, our partners face declining cocoa production

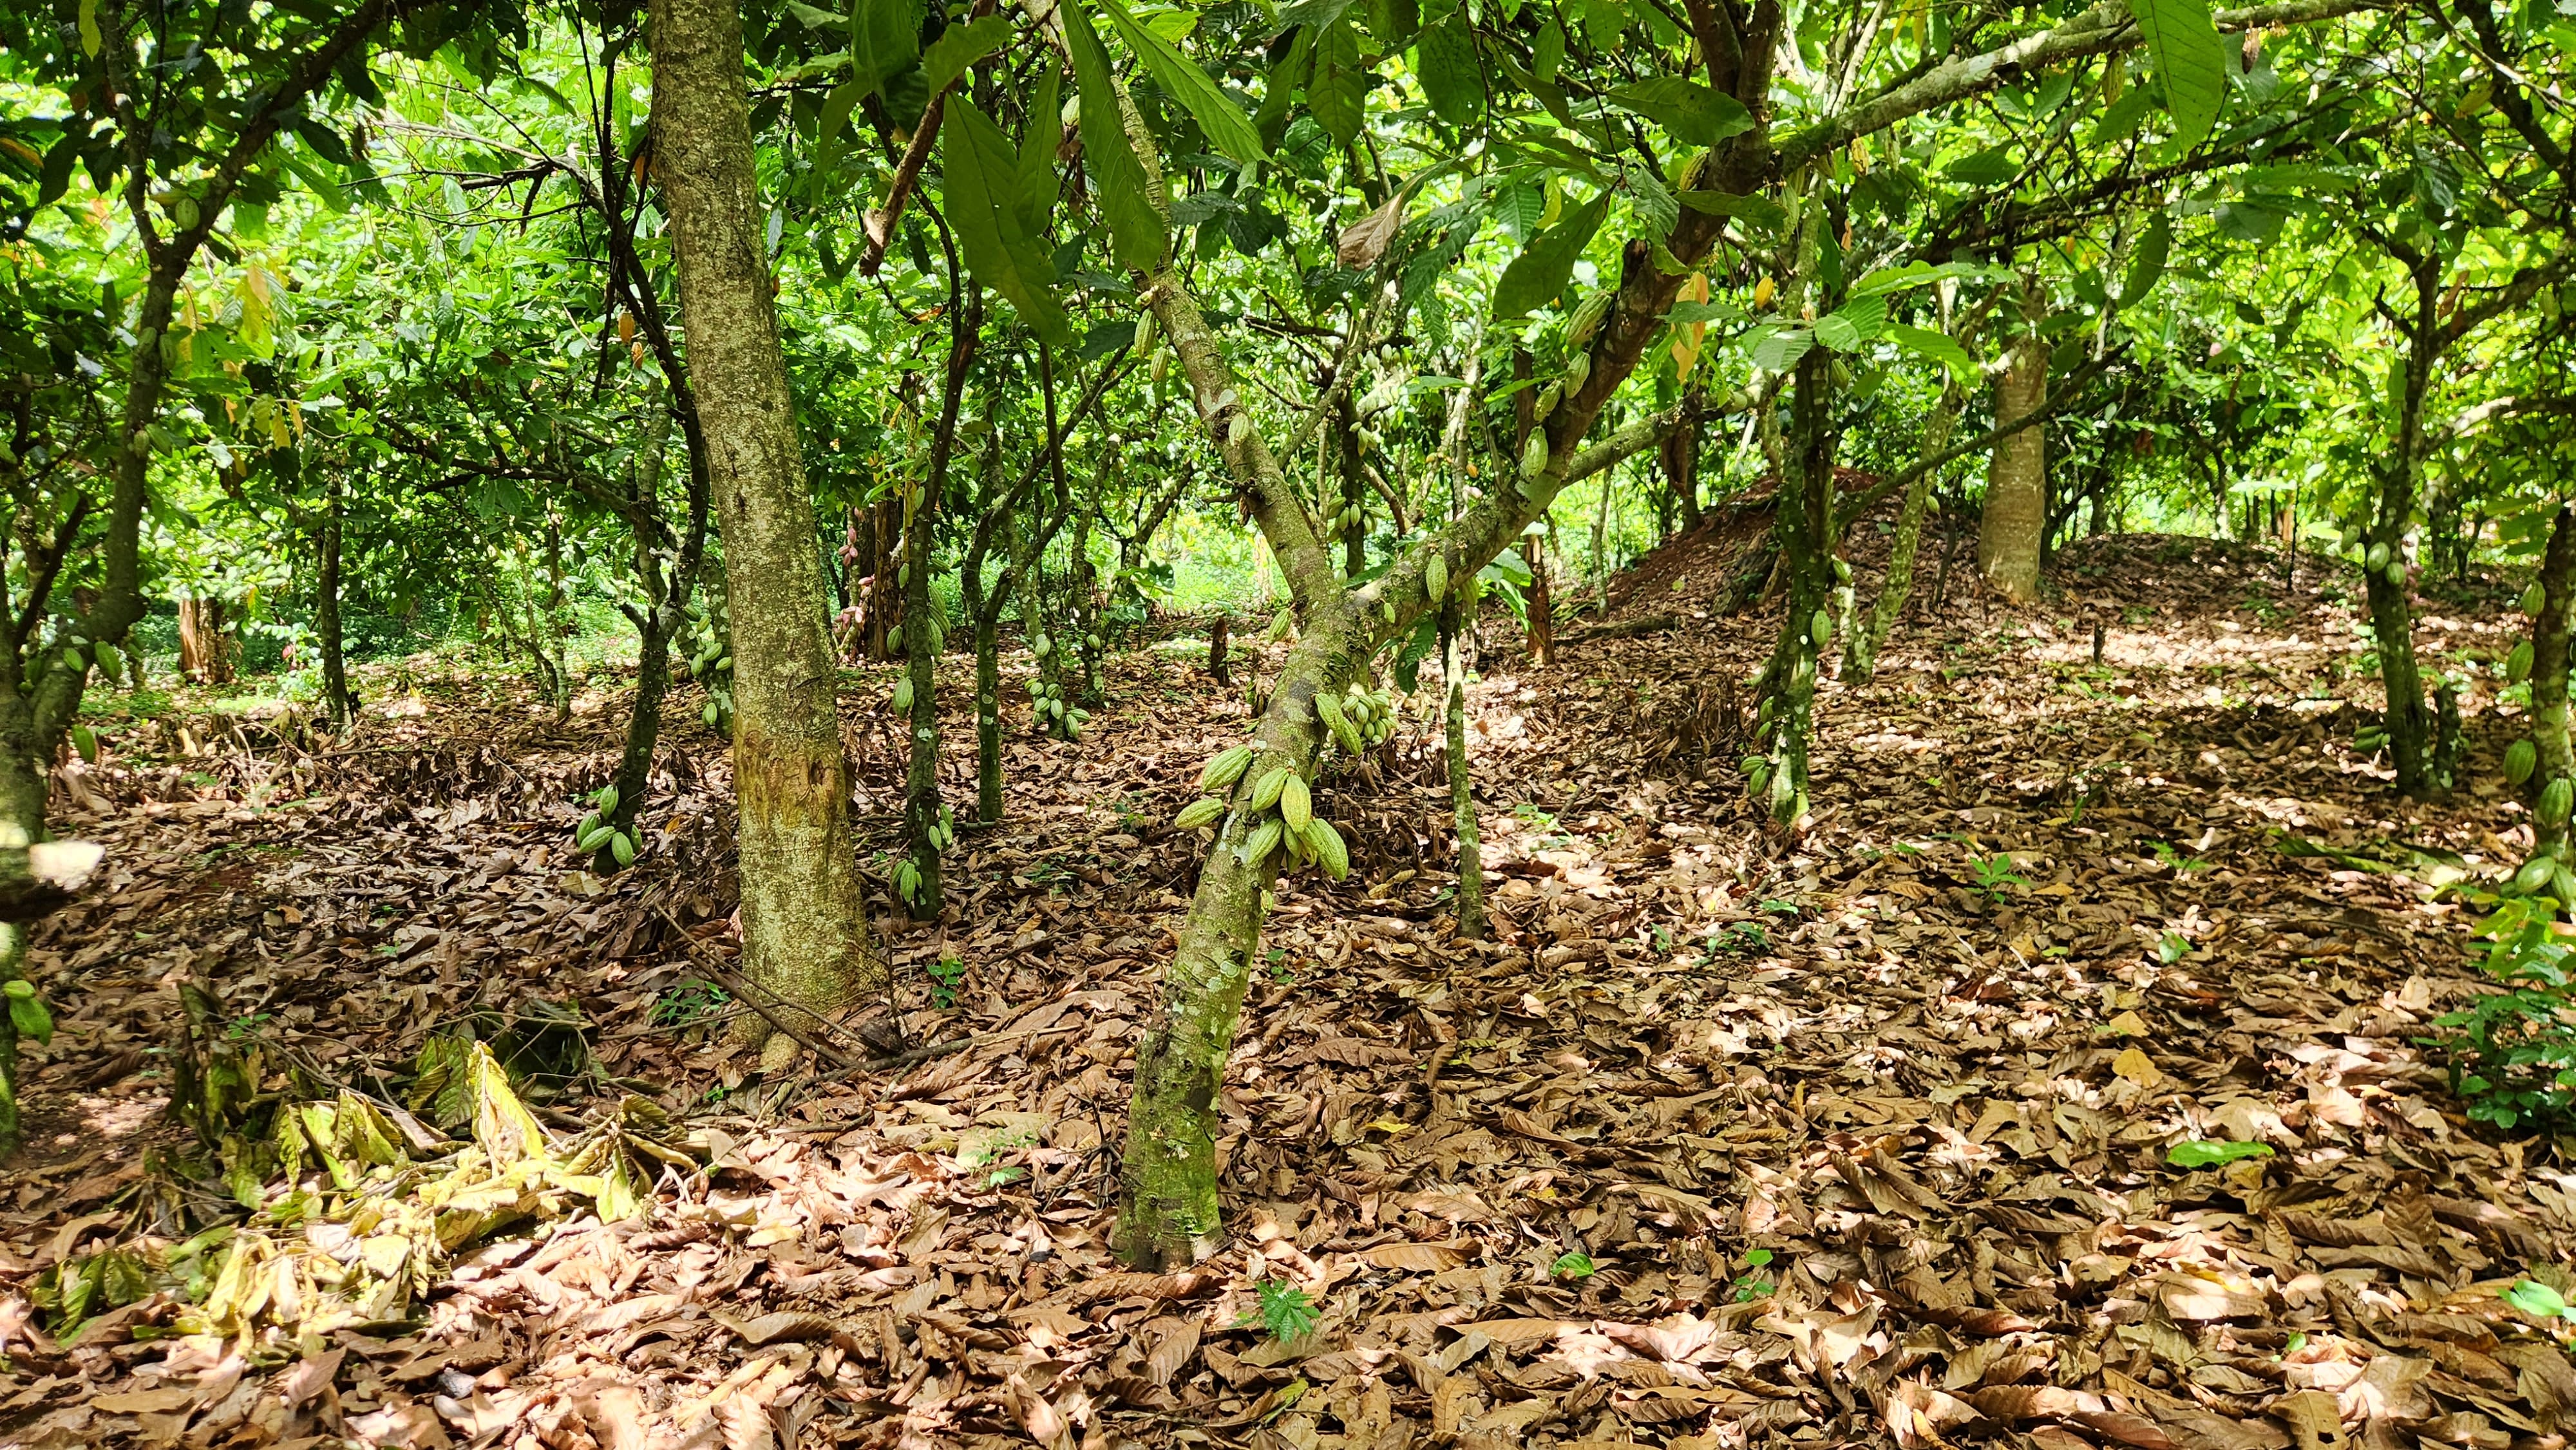
Plants cacao 5 Cote d'Ivoire

Mission feedback: every quarter, a member of SIDI's operational team shares with us a mission carried out with partners and their beneficiaries.

Have you noticed the soaring price of your favorite chocolate lately? Rising prices present a number of challenges for our partners involved in the cocoa sector in Ivory Coast, a country which alone accounts for almost 40% of the world’s cocoa production. Junior Tombe, investment officer, has just returned from a mission to shed some light on the situation.

Since September 2023, I have been in charge of monitoring SIDI’s partners in several West African countries. This is how I discovered Côte d’Ivoire, one of SIDI‘s intervention countries. The changes taking place in the country’s agricultural sector make each mission exciting.

This time, my mission concerned the cocoa sector. We mainly work with certified cooperatives that buy dried and fermented beans directly from producers and then resell them to exporters, often subsidiaries of major chocolate multinationals.

Today, Ivory Coast accounts for between 35 and 40% of the world’s cocoa production (over 50% with Ghana). Any change in production therefore has a direct impact on the world market.

Cocoa futures trading vs soaring world prices

An interesting feature of the Ivory Coast cocoa market is that it is highly regulated. The State, through the Conseil Café Cacao (CCC), sets the price of cocoa at the start of each season: from October 1st to March 31 of the following year for the long harvest, and from April 1st to September 30 for the small harvest. A price scale defines the selling price at all levels of the marketing chain, from planter to exporter. The “bord champ” price is the one paid to growers by the cooperatives. In principle, no one is allowed to buy below or above this price, under penalty of sanctions.

This policy of price stabilization, adopted after the excesses of liberalization, guarantees a minimum price to producers and secures future sales via forward contracts, at prices negotiated six-twelve months before the campaign. However, the last season (2023/24) and the main part of the 2024/25 season were marked by a drop in production: down 25 to 30% in 2023-2024 and lower deliveries for the current season. Caused by climatic disruption – “droughts” alternate with excessive rainfall – the drop in production, coupled with stock market speculation, contributed to the historic surge in international cocoa prices (a tonne of cocoa rose from $4k to $12k between the end of 2023 and April 2024).

Given that the majority of Ivorian cocoa production is sold in advance at pre-negotiated prices, soaring prices have widened the gap between the farm-gate price paid to producers and the market price, ultimately putting a strain on the price stabilization policy. This poses new challenges for cooperatives.

Mature partners capable of anticipating production trends

During my mission, I was impressed by the maturity of our partner cooperatives in the face of these challenges. They have succeeded in delivering 80% of their contracts to buyers in the 2024/25 long harvest.

This demonstrates their level of local knowledge and the effectiveness of their producer loyalty strategies. Against a backdrop of falling cocoa production, which can intensify competition, the benefits our partners provide to their members are decisive in securing the stock: supply of inputs, school loans, training, donations of tools, and so on.

In addition to focusing on non-commercial services, our partners have anticipated the increase in their financing needs. This is how they obtained larger amounts of pre-financing from buyers, in addition to increasing the amounts of their loans negotiated with SIDI (+1.1 M€ of loans in 2024 compared to 2023).

Unlike buyer advances, which are repaid on delivery, and bank loans, which are often amortized monthly, SIDI loans offer flexible working capital, as they are repaid on the last deliveries.

The example of ECAM, an emblematic SIDI partner since 2017

Based in Méagui in southeastern Côte d’Ivoire, ECAM has over 3,000 members and a production capacity of around 7,000 t of cocoa.

During my visit to ECAM members’ plantations, I became aware of the cooperative’s resilience, as some plots have been affected by swollen shoot disease for several years. This disease, which is incurable to this day, destroys the branches and leaves of cocoa trees, leading to a drop in production for producers and, consequently, a fall in income. To counter this scourge, ECAM is promoting crop diversification by distributing vegetable seeds to supplement cocoa in infected areas. This is in addition to the activities of ECAM’s sustainability program: promotion of organic inputs to support productivity, distribution of shade trees, etc.

SCEB, a 100% organic cooperative that could become a new partner

This mission enabled me to meet a potential new partner for SIDI: SCEB, a 100% organic cooperative, quite different from what we see in Côte d’Ivoire.

For SIDI, it’s important to support a partner that chooses organic agriculture in a context where less than 10% of the members of partner cooperatives are organic, and where the European Union, the main buyer of Ivorian cocoa, is strengthening its legal measures to combat deforestation.

The cooperative’s positioning in this niche market, in a country where cocoa is almost exclusively grown conventionally, sets an example for other cooperatives.

All in all, it has been truly enriching for SIDI to support these partners in the cocoa sector in Côte d’Ivoire, who have shown a great capacity to adapt. I’m convinced that the Côte d’Ivoire experience can be a rich source of lessons for other countries and other sectors.


Interview by Anne-Isabelle Barthélémy

Image credits SIDI: cocoa plants, shade tree nursery, on the road, a cocoa tree affected by swollen shoot.
 

Resisting in times of conflict: the testimony of Hekima, a partner based in the Democratic Republic of Congo, at SIDI’s General Meeting

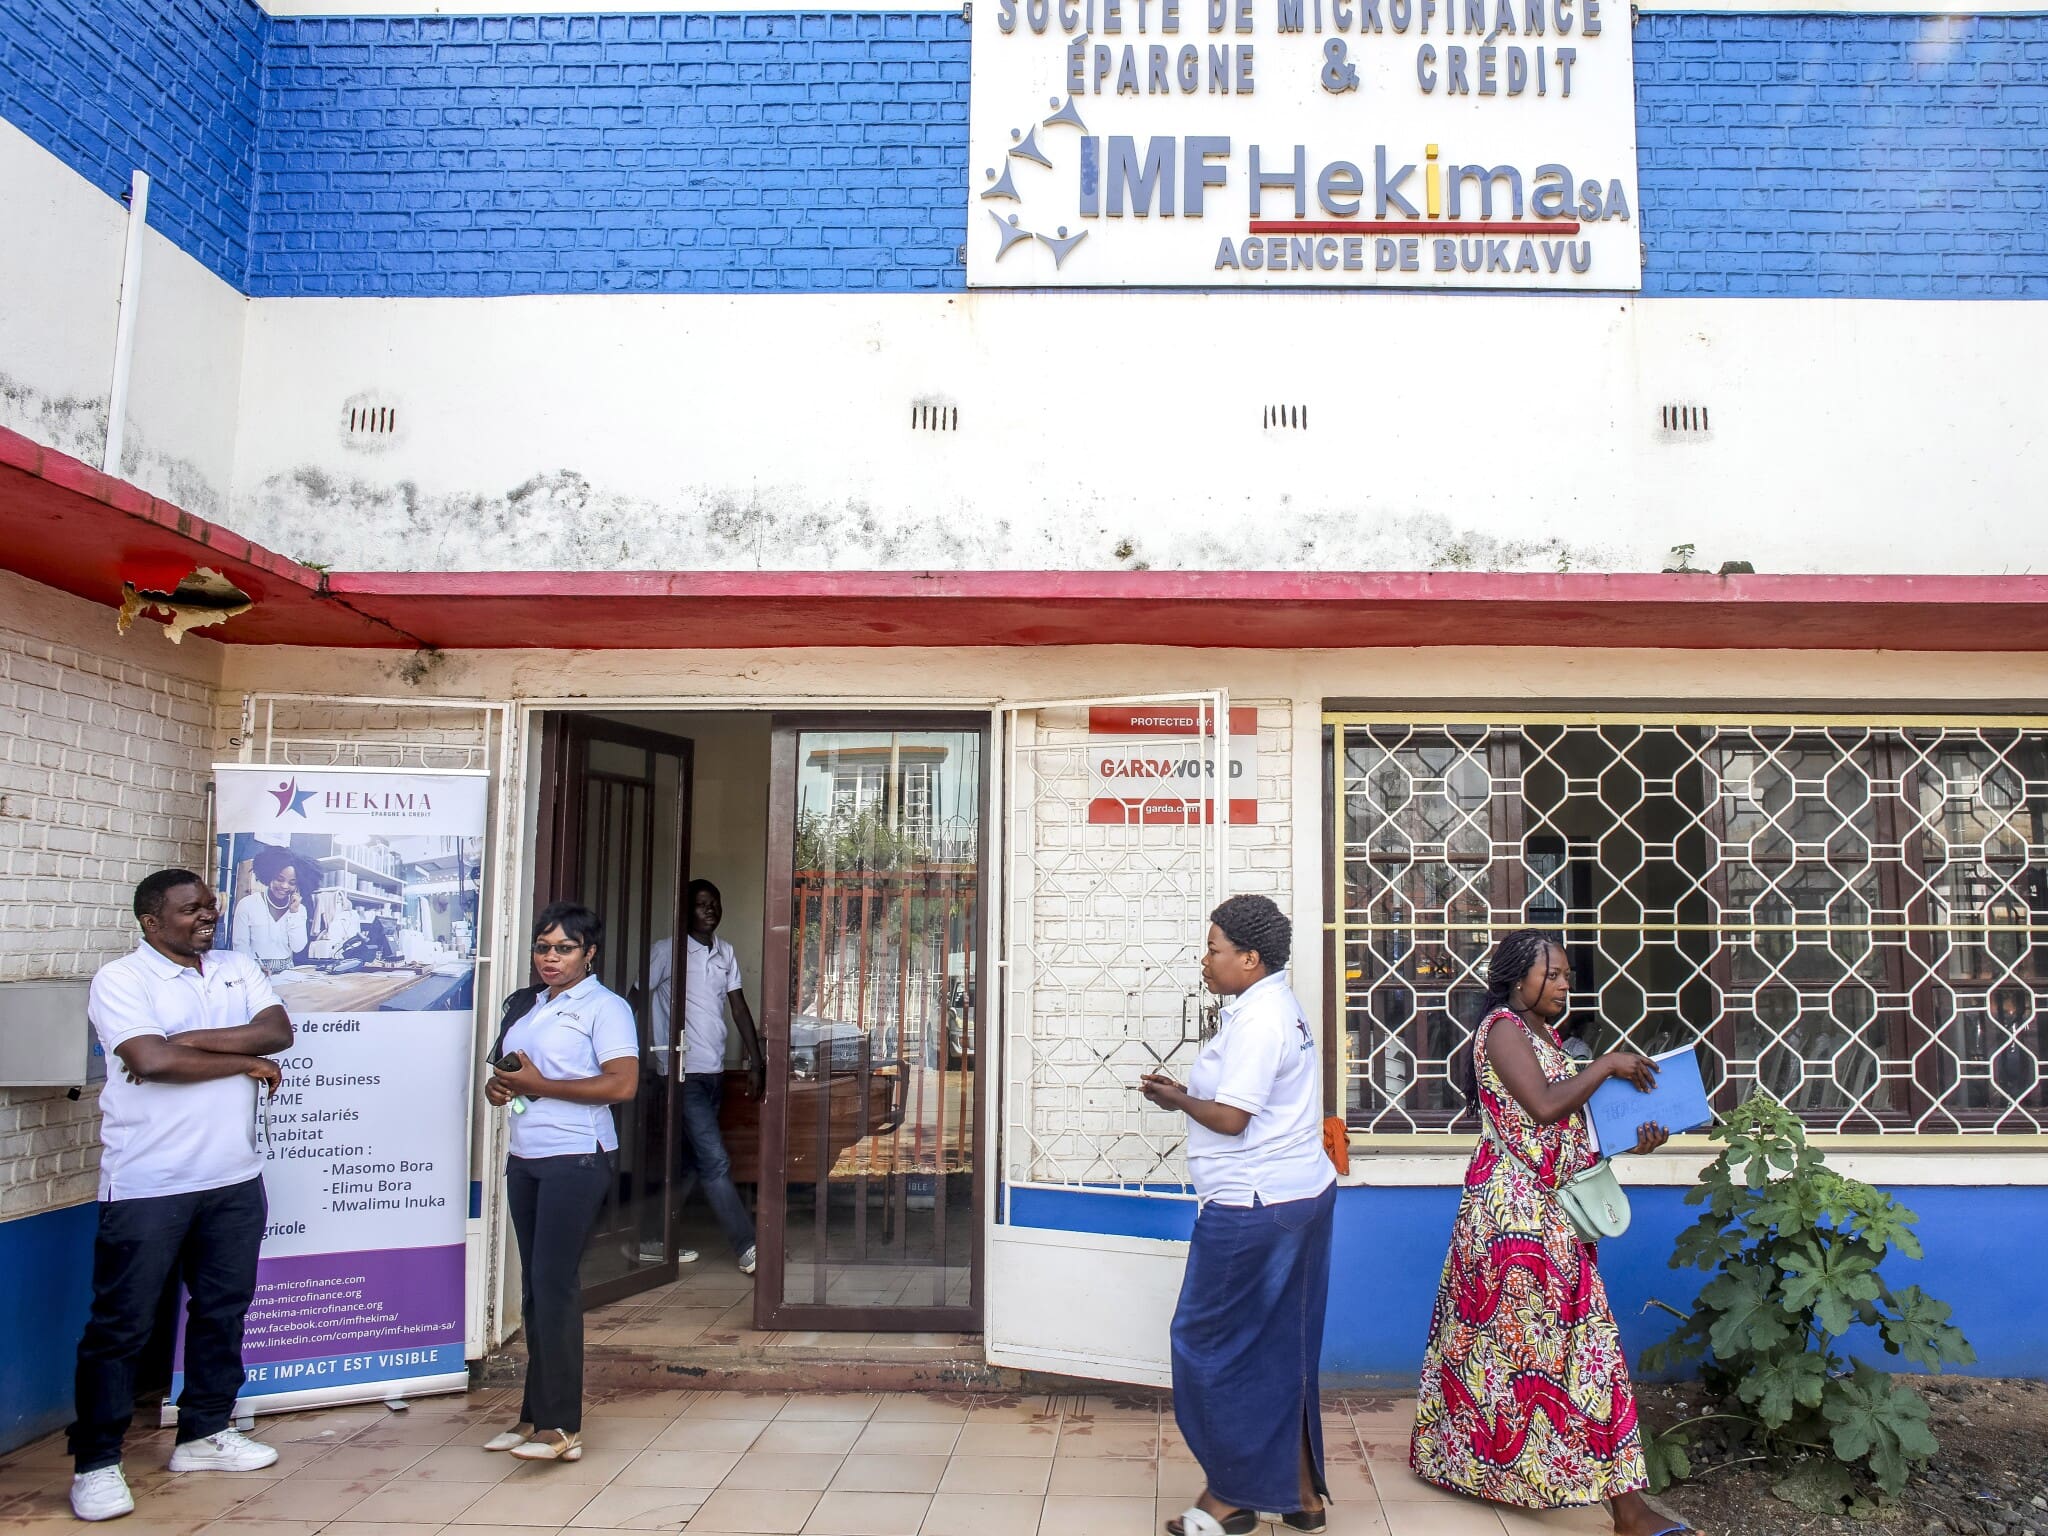
Hekima took part in SIDI's Annual General Meeting on June 11 to give us a better understanding of the role of microfinance institutions in Kivu, a region marked by armed conflict and high levels of insecurity, and of how Hekima manages to pursue its activities in this context.

Like every year, the Annual General Meeting is an opportunity for SIDI to invite one of its partners to speak. This year, we were delighted to welcome Laurent Daddy Yamba, Director of the microfinance institution (MFI) Hekima partner of SIDI in the East of the Democratic Republic of Congo (DRC).

A partnership between Hekima and SIDI based on trust

The first contacts between Hekima and SIDI date back to 2013, and the partnership officially began in 2021. It is based on great trust. In terms of financing, SIDI and FEFISOL (European Solidarity Fund for Africa)financent Hekima up to1.5 million since 2021. At the same time At Hekima’s request, SIDI joined its Board of Directors, contributing to the debate on its strategic and controlled development: portfolio growth, digitalization, expansion in a high-risk area.

Hekima and the situation in Kivu

Laurent D. Yamba explained how Hekima continues to work in a difficult context: since January 2025, the offensive led by the M23, a rebel group active in Kivu supported by Rwandan soldiersaishas led to atrocities, displacement of populations, economic losses and widespread insecurity, all of which are undermining the MFI’s activities (see our article on the M23 takeover of Goma and the impact on our partners and the population). On June 27, a peace agreement was signed between the DRC and Rwanda, but the situation remains uncertain.

Founded in 2007, Hekima is an MFI headquartered in Goma and through three three other branches in Bukavu, Kalemie and Lubumbsahi. It had 8,119 active borrowers and a loan portfolio of $9.7 million at the end of the first quarter of 2025. The MFI mainly targets women entrepreneurs (78% of its clientele), notably through group loans (inspired by local tontines) mainly in urban areas, due to the risks associated with the informal agricultural sector.

Since January 2025, cash has been in short supply, so MFIs have become strategic structures, but also particularly exposed, endangering Hekima’s activities and team. Between violence against customers, looting of borrowers’ businesses the economic slowdown and logistical difficulties, Hekima, like all other MFIS in the region, has had to scale back its operations.

Laurent Daddy Yamba is currently in Kinshasa for security reasons. Exchanges with customers have become difficult, as have loan rescheduling. While some MFIs are still holding out, many mutualist structures “only hold out in name. They’re dead.

“Microfinance institutions are dying and need support – and they’ll need it even more tomorrow, when the crisis is over, because we’ll need to restart operations.”

Maintaining business despite conflict

Despite all this, Hekima continues to operate and serve its customers, constantly adapting. Fallback points are organized for fund-raising and distribution, sometimes in hotels. The team, though dispersed, continues to work from home, arranging appointments at the safest times. All remain hopeful and committed to their mission, despite the civil war.

This business continuity has strengthened customer confidence in Hekima. In Goma, from March to May 2025, the MFI was able to finance 476 loans for a total of $246,000, in the form of small loans of around $500, in a region where cash is scarce and crucial for access to healthcare or food. In these complex times, Laurent Daddy Yamba explains how Hekimato loans to as the impact is greater.

What solutions for tomorrow?

Laurent Daddy Yamba also lobbies international and national institutions and national institutions – IMF, World Bank, Central Bank of Congo – for the creation of a recovery fund for the post crisis. In fact, no MFI can cope with the upturn in activity on its own. . This stimulus fundwould three components: 0-rate loans, subsidy funds – either for equipment or for the portfolio – and the rapidly usable financial guarantees. For Laurent Daddy Yamba, such asuch a stimulus fund is essential to restart operations as soon as security conditions allow customers to return in large numbers.

A meaningful testimony

Invite Hekima and his Director Laurent Daddy Yamba to our Annual General Meeting is an honour for SIDI, and also a strong way of expressing our solidarity with our partnerthe Congolese people and microfinance players in Kivu. Today, the challenge is clear: to stand by Hekima and prepare for the post-conflict period.

In Lebanon, the fragile renaissance of Al Majmoua and microcredit, despite financial crisis and war

Return from mission: every quarter, a member of SIDI's operational team shares with us a mission carried out with partners and their beneficiaries. For his first mission in Lebanon, Jean-Baptiste Cousin recounts his discovery of our partner Al Majmoua, in a country still reeling from the financial crisis and recent Israeli attacks.

I took over the monitoring of the SIDI partnership for Lebanon in January 2025. A first mission, scheduled for February, had to be cancelled at the last minute due to the excessive Israeli bombardment of Beirut, despite the truce that had been signed. In May, I was finally able to leave, with my colleague Ariane Bevierre and a delegation from ADIE. During this mission, I discovered the resilience of Al Majmoua, the leading microfinance institution in Lebanon, a partner I know little about, but which is perfectly in line with SIDI’s target.

Banks in Lebanon are no longer operational

When I arrived, I discovered a country where there were no banking services and no financial activities. In 2020, following a massive devaluation, the banks confiscated savers’ assets ($90 billion!). The country’s elite got their money out in time. But the rest of the population found their accounts blocked and were unable to withdraw any money, except in small amounts. In recent months, it was still forbidden to withdraw more than 250 dollars a month. At this rate, it would take 3,000 years for Al Majmoua to recover the $9 million sequestered in his accounts. As a result, no one is depositing money with the banks, which are not granting any loans.

With average incomes plummeting and 30% of the population living below the poverty line, the demand for credit is enormous. The only recourse is money from the diaspora or microfinance. The problem? No donor wants to go to Lebanon any more because of the losses incurred during the crisis.

Lebanon’s financial crisis nearly wiped out our partner Al Majmoua

Before the crisis, Al Majmoua was a highly successful financial institution, managing over 100,000 loans. At the time of the crisis, it found itself on the verge of complete bankruptcy. With the devaluation of the Lebanese pound, its portfolio lost 99% of its value, given the exchange rate imposed. The association lost all its financial assets in the turmoil: $50 million!

The association’s bankruptcy was avoided thanks to the settlement of its debts by the donors, who assumed losses of $50 million, including $1 million for SIDI.

Loans repaid on time and on budget

After almost disappearing, Al Majmoua continues to operate with caution. With the little money it has, it issues modest loans averaging around $500. This enables it to reach more people. By April 2025, it had 23,000 loans outstanding. Of these, 85% are to support economic activity.

In Beirut, I visit a Palestinian chicken seller. The ceiling of her store collapsed during the Israeli bombardments. The loan will enable her to repair the ceiling, so that she can continue her business and gradually pay back her loan instalments.

Against the backdrop of Lebanon’s financial crisis and war, I’m impressed by Al Majmoua’s loan recovery rate of 98%. Including in bomb-ravaged southern Lebanon and the Bekaa plain.

Among the loan beneficiaries I met, I felt a strong sense of identification with Al Majmoua and recognition. For them, nothing is more important than paying, because Al Majmoua is the only entity that can lend them money for their projects. They hope that the association can continue to help them get back on their feet.

A global vision in the fight against poverty

I totally identify with Al Majmoua’s approach.

For Al Majmoua, microcredit is not an end in itself, but first and foremost a means of combating poverty. The association carries out both financial and non-financial activities. To support its members, it acts on various levers: financing, but also education and organization. For example, it offers a financial education program: how to manage a loan, a budget, a forecast. It’s a basic entrepreneurial culture that’s extremely important if you want to get out of poverty.

This posture is not so common in the world of microfinance. But it is totally in keeping with SIDI, which offers both financial services and support.

For me, this global approach is the most effective way to fight poverty. Because poverty has many facets, and credit alone solves nothing.

Supporting the rebirth of Al Majmoua

It’s not easy to think about lending again in Lebanon. SIDI (or rather FID, the guarantee fund backed by congregations, CCFD-Terre Solidaire and SIDI itself) has had to cover major losses. But this seems to me to be the right time to support Al Majmoua in its redeployment, at a time when so few organizations are backing it. It’s an institution that seems to me to have the potential and the qualities to turn itself around.

In a context where poverty has exploded, the demand for microcredit is very high. But so far, no one wants to return to Lebanon. Wouldn’t it make sense for SIDI, which “wants to go where others don’t go”, to get involved again?

It’s our job, as partnership managers, to maintain this balance between preserving the resources of SIDI’s shareholders and fulfilling the mission they entrust to us.


Interview by Anne-Isabelle Barthélémy

Photo credits: Philippe Lissac – agence Godong /SIDI; except ADIE cover photo